
By Benjamin Gilad
In two previous posts I featured the relevance of Porter’s insights to Competitive Intelligence professionals struggling with ad hoc information requests and few or no frameworks to think about the big picture. My CIP™s know this, practice this and use it. But there are many Competitive Intelligence practitioners out there who are still performing information tasks with little future in them. So, maybe this series of Porter-in-Action provides them with some value.
It’s either this or the Harry Potter series.
Change Drivers
Porter postulates four main change drivers driving structural change in industries’ five forces (structural change- change in bargaining power). Below I showcase three of them in action, and in the process, why our most critical role is Strategic Early Warning (SEW), and why often, it feels like a hopeless struggle against deaf management. Porter himself expressed frustrations with powerful CEOs’ short-term thinking, so no wonder we are fighting windmills at time. But – and it is a big BUT- we must always try to do SEW, or the designation “CI analyst” is meaningless and we might as well be called glorified archivists and go the way of the dinosaurs or the office typists.
SEW is our hardest task. It feels like a struggle against deaf management. But you must, absolutely must, try it or forever be thought of as a glorified archivist
Change driver 1: Technology.
Most of you recognize the effect technological change can have on your company. The question of early vs late adoption is a big challenge to management and CI professionals alike.
However, in the Big Picture, adoption of technology, or failure to adopt, is not limited to individual companies in a few industries. It seems to lead to continental divide.
Data show American companies are now outpacing their European counterparts in growth and innovation, and the European Central Bank attributes the US outpacing Europe to “labor market churn and higher investment in digitalization.”
Nicolai Tangen, head of the Norwegian $1.6 trillion Norges Investment Bank Managements, says it more succinctly: “It [is] difficult to do business in Europe due to the increased red tape around technology — artificial intelligence (AI) in particular… in America you have a lot of AI and no regulation; in Europe you have no AI and a lot of regulation.”
“…in America you have a lot of AI and no regulation; in Europe you have no AI and a lot of regulation.”
Regulations tend to protect large companies, especially those considered “vital” to national interests (or “crony” companies) from more advanced technology at the hands of competitors and substitutes (two of Porter’s 5 forces). While technological change keeps US companies on their toes, a more “relaxed” competitive mindset among many risk-averse European executives keeps Europe behind. It also means less interest in strategic early warning as well.
Technology change driver can wreck continents, not just companies
In Porter’s 4-corner model, attitudes play a big role in strategy. They are expressed in management Assumptions and Company’s Drivers. Norges’ CEO Tangen points to the “pro-business mindset of the U.S., which stands in stark contrast with his home continent.”
I wonder- do these attitudes affect European CEOs’ use of competitive intelligence as well? Since ACI withdrew from the European market for general lack of profitability compared to the US, I admit, I don’t have a clear answer. But I do know that the change driver of technology eventually transforms the competitive landscape in a radical way despite all protections by political or bureaucratic barriers, and therefore European CI practitioners need to drag their companies by the hair to face the changing competitive reality.
I don’t envy European CI practitioners. But they must be the canary in a gold mine (or bitcoin mine).
Change Driver 2: Government
The retail pharmacy business in the US is in trouble. CVS Health announced this month that it is laying off 2,000 workers, on top of the 5,000 layoffs it announced last year. It shuttered 900 stores in recent years. Rite Aid recently emerged from bankruptcy, and Walgreens plans the closing of one-fourth of its 8,600 stores. This is a radical change.
Why are retail pharmacies failing? There are several change drivers working together, but the government role should be highlighted. Says CVS spokesperson, “Our industry faces continued disruption, regulatory pressures and evolving consumer needs and expectations.” Post government mandated lockdowns, customers simply didn’t return to brick-and-mortar stores. Regulatory pressures on drug prices added to lower profitability. Walgreens CEO Tim Wentworth said in June. “The current pharmacy model is not sustainable.”
The worst effect has been on independent pharmacies, where Biden Administration’s mandate for lowering PBM’s performance fees charged to pharmacies for dispensing Medicare prescriptions backfired. The irony, as always, has been that “Pharmacist groups supported the Medicare rule change, but they didn’t anticipate the PBMs’ response, which has been to demand they accept new contracts with draconian cuts to their payments for dispensing medicines.”
Using government as a strategic tool is common practice but it’s a double edge sword. CI professionals are in the best position to delve into potential response of affected parties.
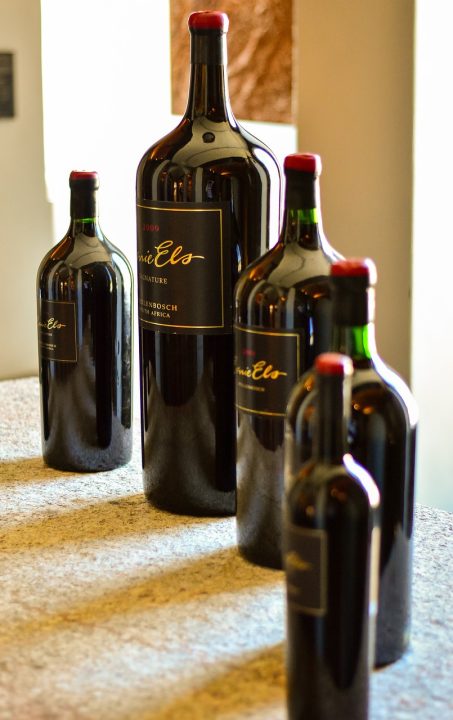
I assume that Competitive Intelligence professionals working in Pharmaceutical companies are paying attention. This is a structural change – not a tactical event- where the bargaining power of distributors shifts to two giants- Amazon and Walmart. They might want to look at what happened in the wine industry in FL in March 2024 when at last, Florida dropped a law that forbade the sale of large bottles of wine since 1939.
We all think of government regulations as serving the “greater good” and not as a strategic tool in competition. Alas, it is more often a tool to serve the interest of some players in the 5 forces. As the story of why Florida outlawed selling wine in large bottles shows, a1939 ridiculous regulation outlawing large bottles was the result of “a near-constant battle between producers, wholesalers, and retailers.” In other words, it was crafted by the wholesalers to prevent the bargaining power of retailers from increasing (by buying huge bottles and rebottling themselves into smaller ones.) This regulation took 85 years to overturn. Government is very often a tool in competitive strategy (or in reality, anti-competitive). But as the Pharmacy story shows, it’s a double edge sword.
L’Chaim.
Change Driver 3: Social/Demographic changes
In my workshop Competitive Blindspots I point to the above as the most insidious change driver. The reason is that it is clear as day for all to see, but often paralyzes management that is locked into a strategy going against consumers’ shifting sentiments. Nowhere is this clearer than the sad saga of Tupperware. Once a proud direct-to-consumer company selling plastic food containers through thousands of “agents”, Tupperware just closed its last US plant and is reorganizing under a new name in Mexico. There were several reasons for the 78-year-old venerable brand failure, but one that is insidious is consumers’ shifting preference for glass containers.
I hate the social/demographic change driver. Not only is it fickle, but it is so obvious, we tend to ignore it until it is close to demolishing our company
What do you do when your entire strategy is plastic? The resilience of Barnes and Noble suggests not all shifting preferences are fatal, and local market intelligence helps.
Barnes and Noble had been close to bankruptcy by 2018, crushed by Amazon and shifting consumer preferences away from physical books. It was acquired by a PE with a vision, that then hired a smart British turnaround leader named James Daunt (two terms I have never thought I’d use- PE with a vision and a smart British leader.)
Daunt set about copying the indie bookstore model (made famous in the British movie Nottingham Hill) and ditching B&N standardized store model. He let “individual locations build displays and organize stores to best fit their communities.” The new strategy resulted in B&N plan to open 12 new locations this month, “which puts the chain on track to hit its goal of 60 planned openings this year.”
A sentence I never thought I’d write: A visionary PE, and a smart British CEO
Bloody brilliant. This is not only Porter in action – the effect of a social/demographic change driver – but also a competitive insight into how to deal with it. It is also clear why Strategic Early Warning which I consider our most impactful task is so hard. For every company meeting a change driver with competitive insight (or foresight), there are at least 2 charging head-on against the wall and a change comes only when it is in crisis on a deathbed (crushed skull).
Alternative perspective
The famous adage, “It doesn’t matter what the competitors do, it matters what we do” which is a mantra I heard 1000 times from powerful executives should be amended in my not-so-humble opinion to the following:
“It doesn’t matter what competitors do, it matters how we react.”
In my next column, I’ll explore the change driver number 4, Competitive Action, and why the above-amended statement is so critical.
I know you can’t wait. I can feel the excitement building up.
By the way, if any tool out of this Porter series intrigues you (and I will be the first to say, it’s NOT for everyone), I’d be teaching them, and you can practice them, this March.
Also coming in our CIP™-I program in March- Heather and Melissa tackle the use of AI and how to prompt it, trigger it, shut it up, and generally exploit it.
Don’t say I don’t listen, Matthew.