
By Benjamin Gilad
The death of strategy
In my Cross Competitor workshop for CIP™, I teach the use of a visual tool created by Porter called Strategic Clustering (or Strategic Mapping). The tool depicts – in a systematic way- the different approaches to competing by different clusters of companies. The clusters are constructed by “lumping” together companies that follow similar strategic commitments along selected strategic dimensions.
The tool is simple and very powerful in one regard: Executives love this visual which propels many CIP™ into a dialogue with their senior bosses, which is my true goal. The sure way for a career death is anonymity.
The sure route to career death is anonymity
In some markets, though, we observe the phenomenon of competitive convergence to a single big cluster of companies following a broad-base strategy, driven by relentless economies of scale. The end result is that as strategic clusters converge, distinct strategies disappear, just as Porter predicts.
As strategic clusters converge, distinct strategies disappear, just as Porter predicts
What replaces unique positioning (strategy)? Operational focus. While entrepreneurs/founders excel at creating distinct strategies (they have to against incumbents), many (not all!) professional managers prefer a less risky route to success: better, faster, cheaper operations. It buys them some time before nimbler substitutes or new entrants make shareholders unhappy with their performance.
Porter in action: Cable industry
Charter, a cable company using the brand Spectrum for its internet and media offering, has lost hundreds of thousands of subscribers in 2024’s third quarter alone. Its broadband and Pay-Tv model continues to decline against technology competitors (pure streamers), as customers “cut-the-cord.”
Charter is not alone. Comcast is in trouble too. Big legacy networks all look alike.
In Comcast’s case, Wall Street has been musing about the benefits of a spinoff for a while. Back in 2020, analyst Peter Supino, then of Bernstein, said “the status quo is failing as large portions of NBCU and Sky lag their industry’s torrid pace of innovation.” NBCUniversal – part of the Comcast Empire, is home to numerous television networks whose troubles have only grown since then, as more viewers dropped cable.
So what do the Chiefs of those lagging assets do? What they are good at. Says Charter’s CEO, “We executed well during the third quarter, building on our operating strategy…in the future, we have the best, fully deployed network uniquely capable of delivering… a competitive advantage.”
The idea that operating excellence delivers a lasting competitive advantage is a seductive illusion. But when your business is declining and the only thing under your control is improving operations, what else can a CEO say?
Just remember Porter: operational race is no strategy.
Just remember Porter: Operational excellence is not the same as strategy
Strategy as a unique positioning
While Charter’s CEO throws around the term “unique” in vain, Jaguar is fighting to keep it after a decade of losing any uniqueness.
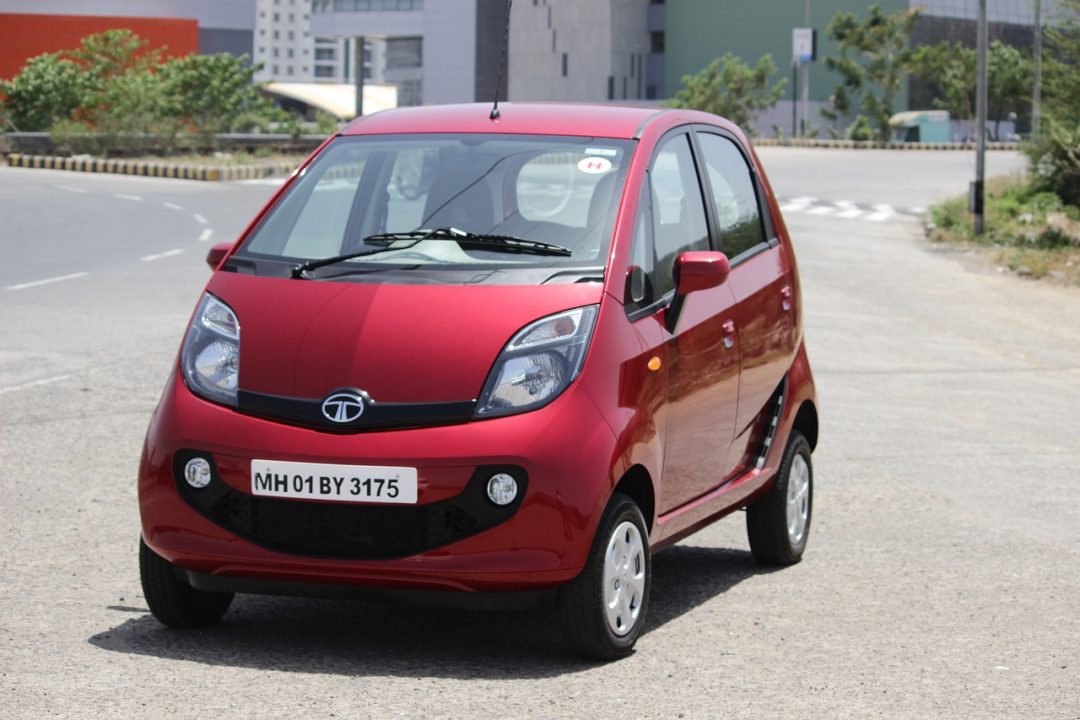
When we analyze movements on the strategic clustering map, there is at times an odd move that can’t be easily explained with just economic forces. Tata, an Indian conglomerate acquired Jaguar and Land Rover in 2008. That move in my mind was at best questionable. Tata was once “known” for producing the cheapest car in the world (the Nano pictured above, image by Alexander Gounder from Pixabay). What did Tata expect to gain? Expertise (from the British???)? More prestigious positioning (which Ford couldn’t)? My rather cynical view conjured a perverse sense of victory over the former colonial masters…
Since the acquisition, Jaguar has been a constant headache to Tata, losing millions. Tata didn’t bring anything to the table to make Jaguar stand out against other luxury brands (a very crowded space). Back in 2020, David Bailey, Professor of Business Economics at Birmingham University said “it’s been trying to be all things to all men but couldn’t compete with companies like BMW. It really needs to focus on niches.” Jaguar seems to have lost a sense of where it stands in the market.
Maybe Jaguar should have hired a CIP™ to do the strategic map for it, though I doubt the Brits or their Indian overlords would listen to anyone but themselves.
Then 2024 cometh… and as Jaguar is down to very few models, and announcing an unprecedented suspension of production, and a vision of EV only models, rumors are flying of Tata looking to download it to bigger players. The Chinese might be interested. They’ve done a great job with Volvo.
The irony is that the new boss of Jaguar – Rawdon Glover- understands the need to get out of competing everywhere trying to reach economies of scale: “We need to take [the brand] back to when we made beautiful desirable cars, not in huge numbers and not having huge numbers [of models] in the portfolio.”
It might be too late, but at least the thinking is right- against EOS you don’t compete by looking like others.
Alternative perspective
What alternative perspective? If you don’t have strategy, and you don’t have EOS, you are doomed. If you have EOS but no strategy, the winner is the one with bigger… pockets.
Or you can run a war game to generate some options for uniqueness.
Our next CIP-I™ will be in March 2025. If you don’t want to end like Jaguar, convince your boss we are the next best thing to economies of scale.